We Bought Our Cabin With a 7.6% Interest Rate. Here's Why I Don't Regret It.
Why waiting for the perfect mortgage rate could mean missing out on the right opportunity.
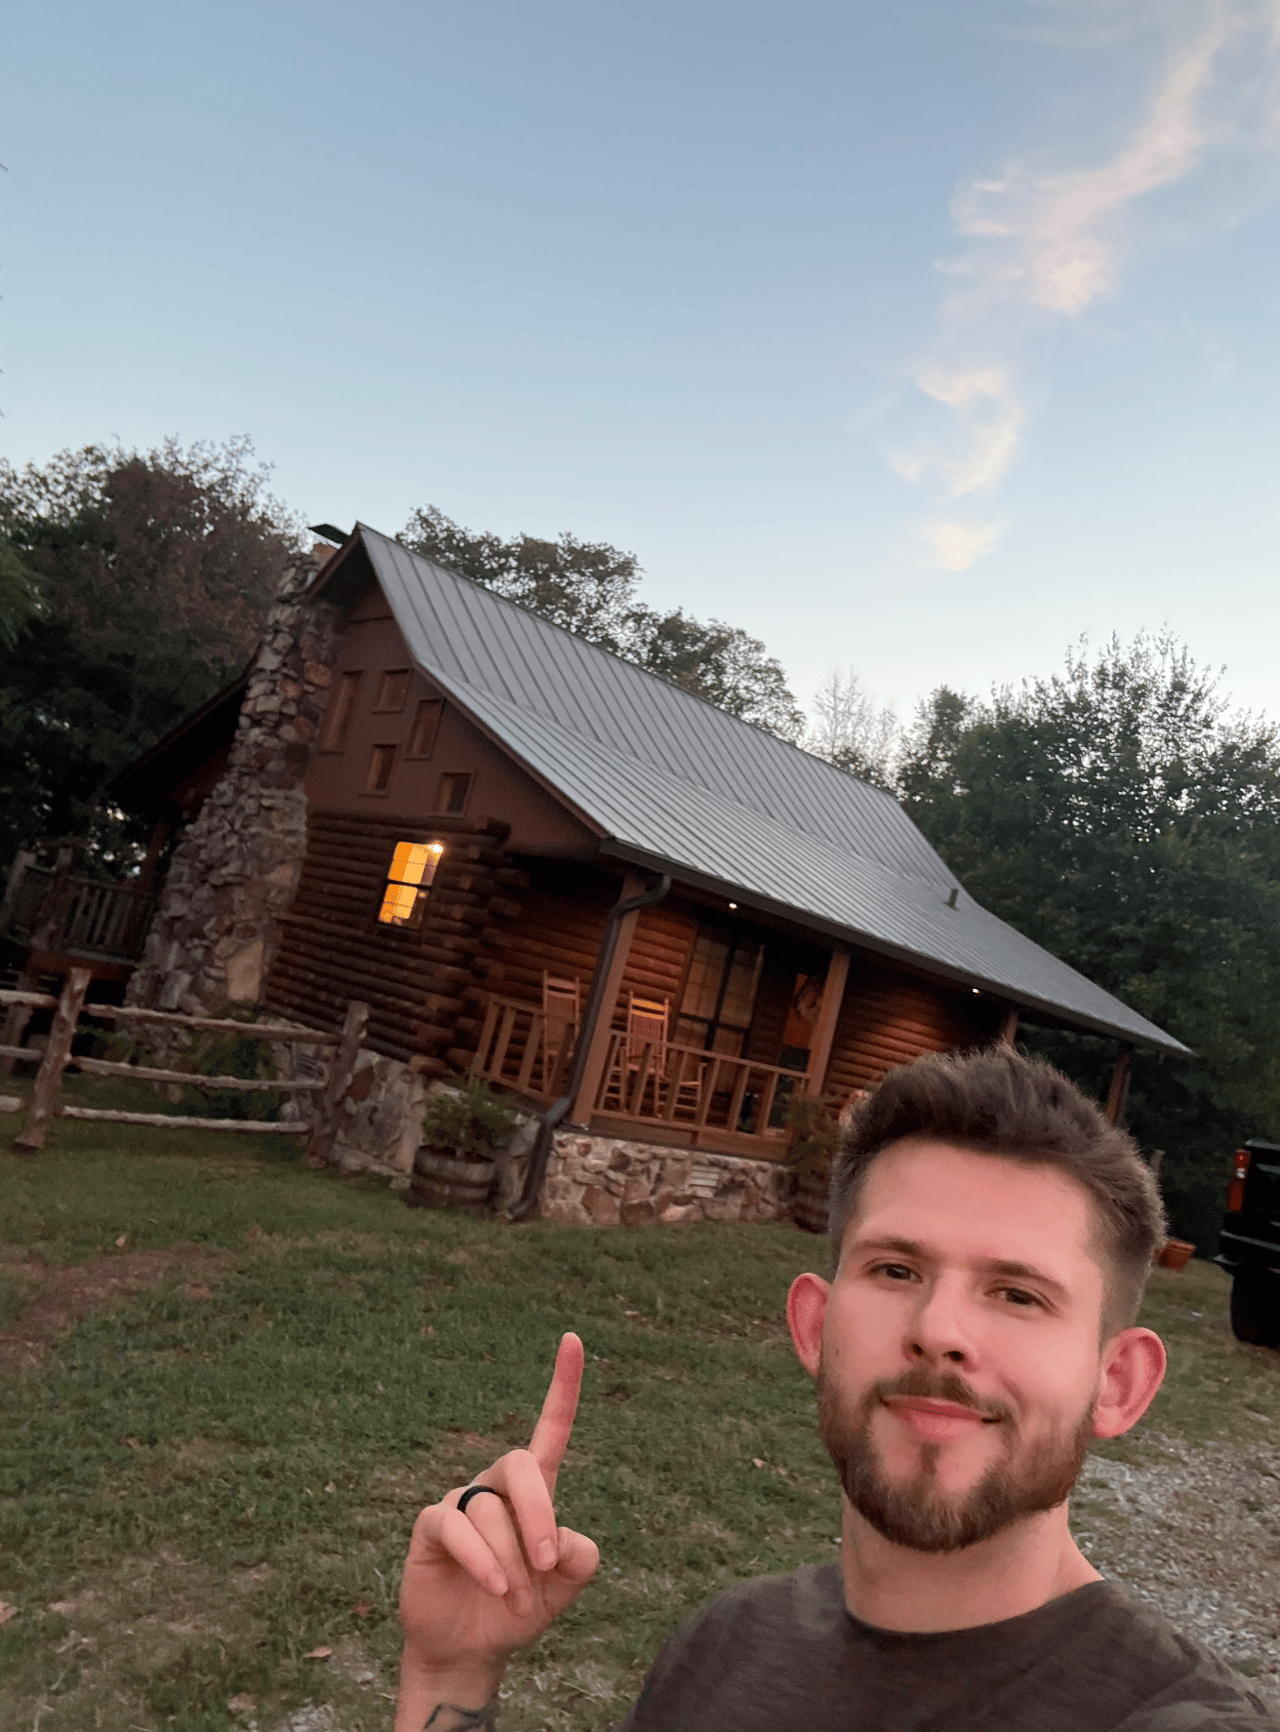
It's been almost a year since my wife and I purchased the little cabin we now call home.
And looking back, I'm reminded of something I've learned through buying multiple properties over the years:
The best time to buy a home isn't necessarily when interest rates are at their lowest. It's when the opportunity makes sense for you.
When we purchased our cabin, mortgage rates weren't exactly attractive. We locked in a rate around 7.6%.
Would I have preferred a 3% interest rate? Absolutely.
But we loved the property, the numbers worked for our situation, and we knew it was somewhere we wanted to call home.
So we bought it.
And nearly a year later, I'm glad we did.
The Most Common Thing I Hear From Buyers
As a REALTOR® here in Central Arkansas, I talk with people every week who are considering purchasing a home.
One of the most common things I hear is:
"I think we're just going to wait until interest rates get back down to 2–3%."
I understand that thinking. Nobody wants to pay more interest than they have to, especially when purchasing what will likely be one of the largest investments of their life.
But here's something I wish more people understood:
Those 2–3% mortgage rates weren't normal. They were historically extraordinary.
During 2020 and 2021, the pandemic created massive economic uncertainty. The Federal Reserve responded with extraordinary monetary policies, including bringing short-term interest rates near zero and purchasing mortgage-backed securities.
Those actions, along with broader economic conditions, helped push mortgage rates to historic lows.
For a period of time, buyers were able to lock in 30-year mortgages at rates that previous generations could have only dreamed of.
But that doesn't mean those rates are coming back anytime soon.
Could they? Sure.
Will they? Nobody knows.
And that's exactly why I wouldn't build my entire homeownership strategy around waiting for them.
I've Purchased Homes at Different Interest Rates
One thing that has shaped my perspective on real estate is that I'm not just helping people buy and sell homes.
I'm also actively buying and investing in real estate myself.
I've purchased properties in very different markets, with very different financing terms.
One of my more recent purchases was financed around 6.5%, while the highest mortgage rate I currently have is approximately 7.6%.
Those rates certainly affect the monthly payments and overall cost of ownership.
But here's what I've learned:
A higher interest rate doesn't automatically make a property a bad purchase, just like a low interest rate doesn't automatically make one a good purchase.
What matters is the bigger picture.
What did you pay for the property? Can you comfortably afford the monthly payment? Does the property meet your needs? How long do you plan to own it? What are your long-term goals?
Those are the questions that should drive the decision.
Not just the number attached to your mortgage.
The Hidden Cost of Waiting
Let's say you're considering purchasing a home for $250,000.
You decide to wait because today's mortgage rates feel too high.
Your hope is that rates will eventually fall, making the home more affordable.
That could happen.
But there's another possibility.
While you're waiting, home prices in your market could continue increasing.
That $250,000 home might cost $265,000 or $275,000 a few years from now.
Even if mortgage rates fall, the higher purchase price could offset some of the savings.
Of course, the opposite can happen too. Home prices can decline, and waiting may turn out to be the better financial decision.
That's the challenge with trying to time the market.
You're making a decision today based on something nobody can predict with certainty.
Instead of asking whether the market will be better in two years, I encourage buyers to focus on whether buying makes financial sense for them right now.
You May Be Able to Change Your Interest Rate Later
There's another important piece of this conversation.
When you purchase a home, your agreed-upon purchase price is fixed.
Your mortgage interest rate, however, doesn't necessarily have to stay the same forever.
If rates decline enough in the future, refinancing may become an option.
For example, someone who purchases a home with a 7% mortgage might eventually have an opportunity to refinance at a lower rate.
That could reduce their monthly principal and interest payment.
But refinancing isn't guaranteed. It depends on future rates, your financial qualifications, your property's value, and the costs involved.
My philosophy is simple: Buy a home you can comfortably afford at today's rate. If refinancing becomes beneficial later, consider it a bonus.
Never purchase a property you can only afford if rates eventually come down.
That's a gamble I wouldn't recommend.
What About Building Equity?
This is one of my favorite parts of real estate ownership.
Every time you make a mortgage payment on a traditional amortizing loan, a portion of that payment goes toward reducing your principal balance.
Over time, that helps build equity.
And if your property appreciates in value, you may benefit from that growth as well.
Of course, appreciation isn't guaranteed. Real estate markets fluctuate, and ownership comes with expenses that renters don't always face, including maintenance, insurance, property taxes, and repairs.
But for someone who purchases responsibly and plans to own the property long-term, homeownership can be a powerful wealth-building tool.
I've seen that firsthand through the properties I've purchased.
And it's one of the reasons I'm so passionate about helping other people understand real estate beyond just the monthly mortgage payment.
Renting Isn't Always the Wrong Decision
I also want to make something clear.
I don't believe everyone should rush out and purchase a home.
Sometimes renting is absolutely the right financial decision.
Maybe you're still building your savings.
Maybe you're paying down high-interest debt.
Maybe you're uncertain about where you'll be living in the next year or two.
Or maybe the monthly cost of purchasing a home simply doesn't make sense for your current budget.
There's nothing wrong with waiting for those reasons.
In fact, I would encourage it.
What I don't want is for someone who's financially prepared to buy, has found the right property, and can comfortably afford the payment to miss an opportunity solely because they're hoping for a mortgage rate that may not return for years.
There's a big difference between waiting because you're not financially ready and waiting because you're trying to predict the perfect market.
Nearly One Year Later, I'd Make the Same Decision
When I look at our cabin today, I don't think about the interest rate every time I pull into the driveway.
I think about the life we're building there.
The memories we're making.
The opportunity we had to purchase a property that felt right for us.
And yes, I think about the financial side of it, too.
We made the decision knowing exactly what our payment would be. We didn't need rates to fall to make the purchase work.
If rates eventually improve enough to justify refinancing, we'll evaluate that opportunity.
If they don't, we still own a home we love.
That's a decision I'm comfortable with.
And it's the same perspective I try to bring to every buyer I work with.
My Advice If You're Thinking About Buying
Stop asking yourself:
"Is this the perfect time to buy a house?"
Start asking:
"Is this the right time for ME to buy a house?"
Can you afford the payment without stretching yourself too thin?
Do you have enough money saved for closing costs, moving expenses, and unexpected repairs?
Have you found a property that fits your needs?
Do you plan to stay long enough for ownership to make financial sense?
If the answers are yes, buying could be a great decision, even with today's interest rates.
And if the answers are no, that's okay, too.
The goal isn't simply to own real estate.
The goal is to make smart real estate decisions that improve your life and financial future.
That's what I believe in, both as a homeowner and as a REALTOR®.
And that's what I'll continue encouraging my clients to do.
Let's Talk About Your Next Move
If you're considering purchasing a home in Central Arkansas but feel uncertain about interest rates, I'd love to help you work through the numbers.
No pressure. No sales pitch about why you have to buy right now.
Just a conversation about your goals, your budget, and what makes the most sense for your situation.
Because buying a home should be an informed decision, not an emotional reaction to the market.
Dylan Johnston, REALTOR®
Brokered by Howell Realty Pros
📲 501-628-2838
Office: 501-230-2667
Helping Central Arkansas buyers and sellers make confident real estate decisions.